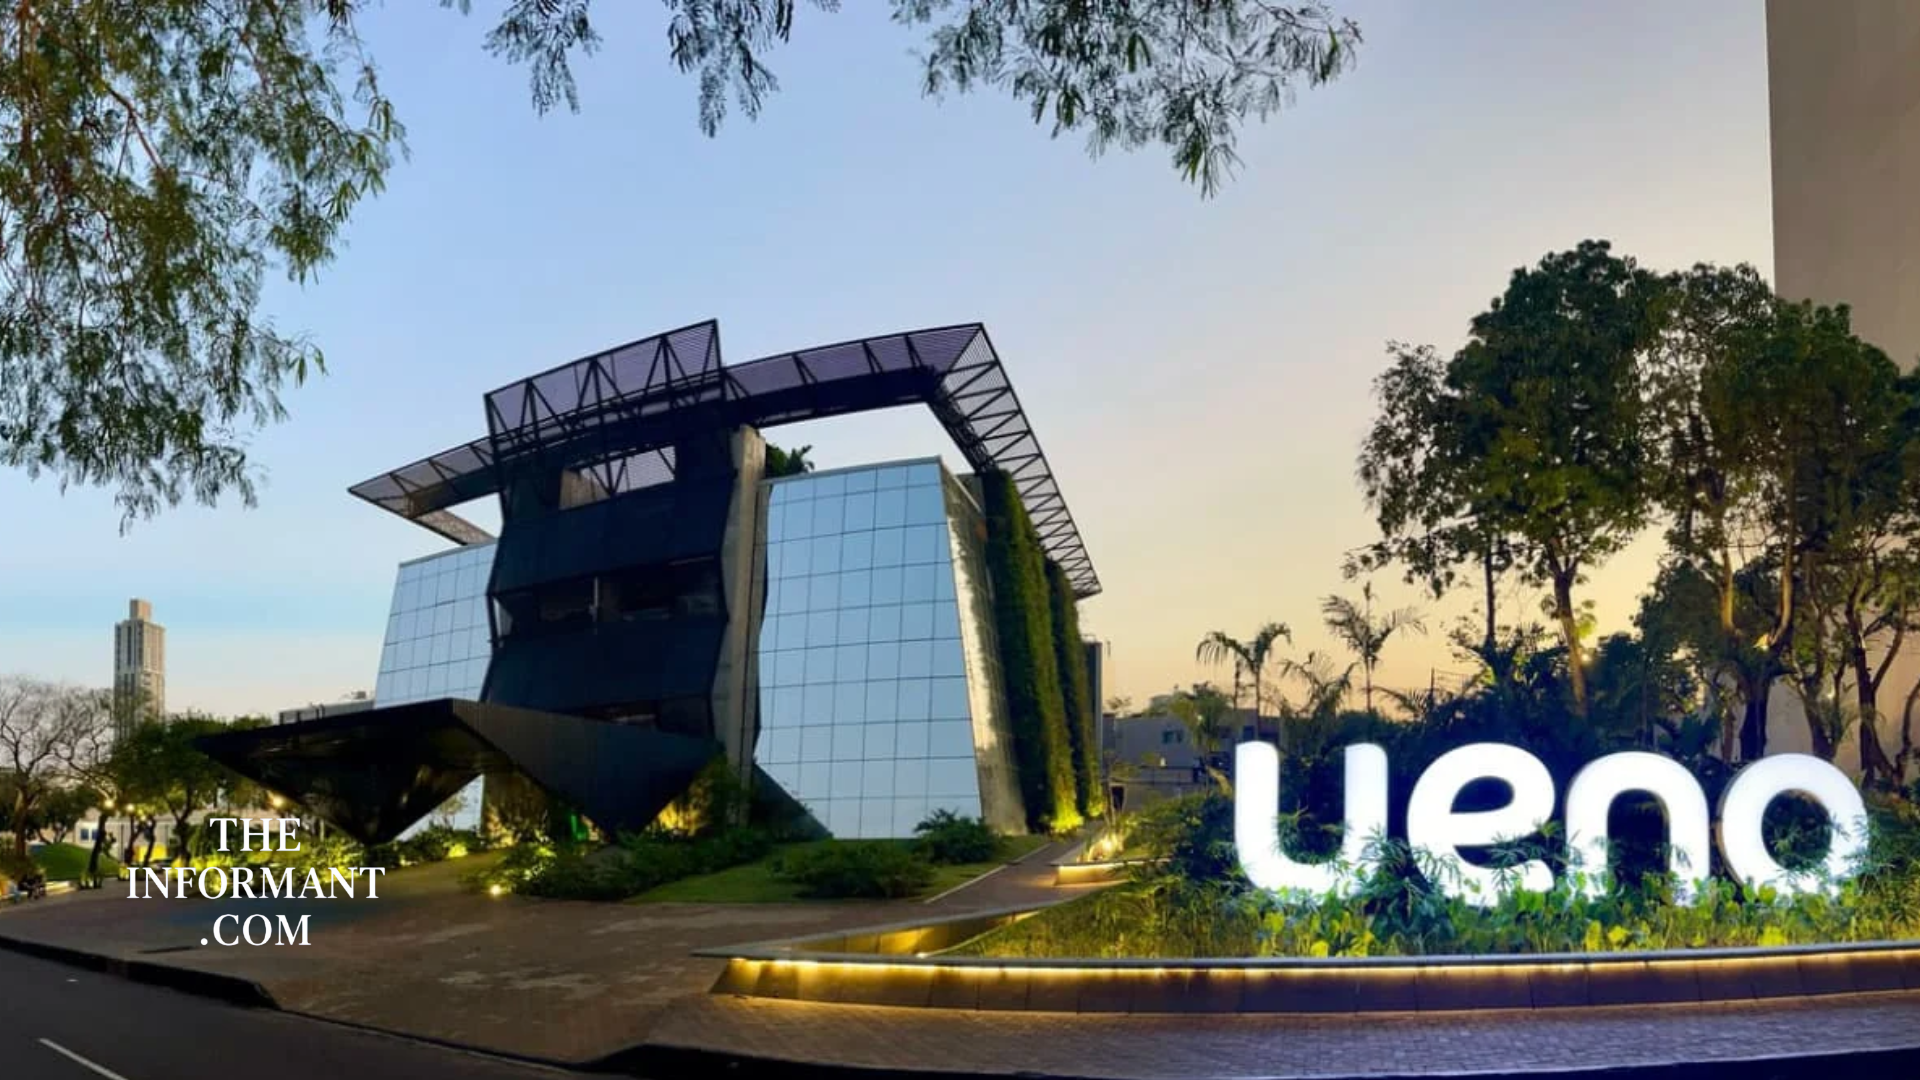
ASUNCIÓN, Paraguay — November 3, 2026. Paraguay’s central bank has taken emergency action against Ueno Bank, one of the country’s fastest-growing digital lenders, after discovering a severe deterioration in its financial solvency. The intervention has temporarily prevented millions of customers from accessing banking services and raised concerns about approximately $2.8 billion in deposits, including substantial public-sector funds.
CENTRAL BANK ORDERS EMERGENCY RESOLUTION
The Central Bank of Paraguay, known as the BCP, announced early Tuesday that its board had unanimously approved the start of a formal resolution procedure on November 2.
Regulators determined that Ueno Bank’s solvency ratio had fallen below 50% of the minimum required under Paraguayan banking regulations.
The deterioration followed adjustments to the institution’s financial statements during a regulatory review.
The central bank said the procedure was intended to protect depositors, preserve assets and prevent the institution’s problems from spreading throughout the financial system.
MILLIONS OF CUSTOMERS FACE ACCOUNT RESTRICTIONS
Ueno Bank has reported approximately 3 million customers, a figure representing a substantial share of Paraguay’s adult population.
Following the announcement, customers reported being unable to withdraw cash, transfer funds, use payment cards or access regular banking services.
Branches were closed as authorities began reviewing the institution’s financial position.
The disruption has created uncertainty for households and businesses that rely on the bank for everyday transactions.
Although the customer count is significant, it does not necessarily mean that every registered customer maintains an active deposit account.
BILLIONS IN DEPOSITS AND PUBLIC FUNDS AT STAKE
Ueno Bank reportedly held approximately $2.8 billion in deposits before the intervention.
International reporting indicates that between $800 million and $850 million in public funds were held at the institution, including deposits associated with Paraguay’s social security and healthcare system.
The presence of public-sector money has intensified scrutiny of the bank’s relationship with government institutions and the financial oversight surrounding those deposits.
The final value of recoverable assets and liabilities will depend on the central bank’s resolution process.
DEPOSIT INSURANCE OFFERS PROTECTION TO CUSTOMERS
The BCP confirmed that Paraguay’s Deposit Guarantee Fund protects eligible deposits up to 75 monthly minimum wages per depositor and financial institution.
The current coverage limit is 228.3 million Paraguayan guaraníes, equivalent to approximately $38,000.
The guarantee applies to each depositor at the institution rather than separately to every account.
Authorities said the fund would begin making initial payments of up to 10 million guaraníes to eligible depositors, with additional payments to follow under a schedule to be announced.
Deposits exceeding the insured limit will be addressed through the resolution process, but their full recovery has not been guaranteed.
REGULATORS EXAMINE FINANCIAL IRREGULARITIES
The central bank’s review reportedly began in June after supervisors identified concerns involving loans to companies linked to Ueno Bank’s controlling business group.
Authorities subsequently examined additional financial transactions and adjustments to the bank’s reported capital position.
The findings contributed to the decision to begin the resolution process.
Investigators are also examining whether bank executives or other individuals may have violated financial regulations or criminal laws.
Any allegations of wrongdoing remain subject to the relevant judicial proceedings.
CENTRAL BANK CHIEF RESIGNS AMID POLITICAL PRESSURE
The crisis has also generated political consequences for President Santiago Peña’s administration.
Carlos Carvallo, the head of Paraguay’s central bank, announced his resignation amid criticism of the institution’s supervision of Ueno Bank.
International reports have highlighted previous business connections between Peña and the bank’s ownership group, raising questions about potential conflicts of interest and regulatory independence.
The president has called for accountability and measures to protect depositors and public resources.
The existence of previous business relationships does not, by itself, establish criminal misconduct by government officials.
AUTHORITIES SAY CRISIS IS LIMITED TO UENO BANK
The BCP emphasized that Ueno Bank’s financial problems represent an institution-specific crisis rather than evidence of a broader collapse of Paraguay’s banking system.
Officials said the resolution process would involve appointed administrators examining the bank’s assets and liabilities and determining how to protect depositors.
The central bank also urged the public to rely on official communications rather than unverified claims circulating online.
Other financial institutions have not been placed under the same resolution procedure as a result of Ueno Bank’s intervention.
WHAT HAPPENS NEXT FOR DEPOSITORS?
Customers are awaiting detailed instructions on how to receive guaranteed deposits and when regular access to funds may be restored.
The resolution process could involve transferring eligible deposits or other assets to financial institutions capable of assuming them.
However, the central bank has not guaranteed that Ueno Bank will resume normal operations as an independent institution.
For depositors with balances above the insured threshold, the eventual recovery of funds will depend on the valuation and disposition of the bank’s assets.
BANKING CRISIS TESTS PUBLIC CONFIDENCE
The intervention represents a major test for Paraguay’s financial regulatory system because of Ueno Bank’s rapid growth, large customer base and substantial public-sector deposits.
While the government has emphasized deposit protection and financial stability, the immediate disruption has left many customers without access to essential banking services.
The outcome will depend on the speed of the resolution process, the protection of insured deposits and the findings of ongoing financial investigations.